

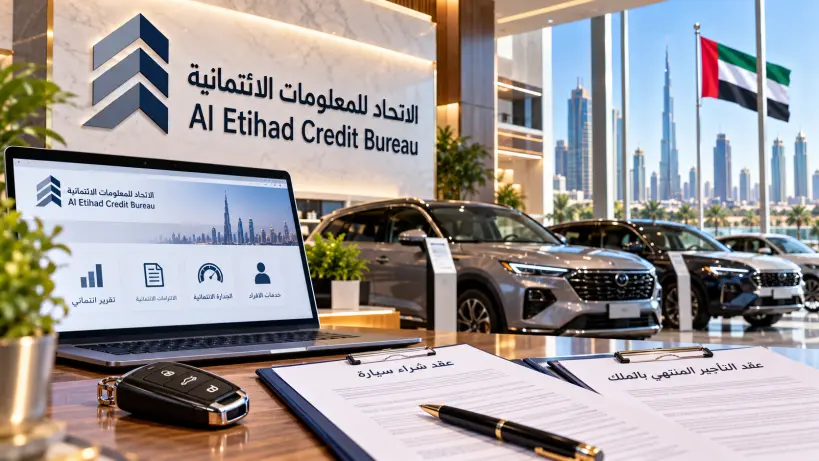
The UAE’s Al Etihad Credit Bureau has clarified important differences between conventional vehicle financing and rent-to-own car arrangements, explaining how each model affects contractual obligations and the use of credit checks before a customer can obtain a vehicle.
In statements published by Emarat Al Youm, the bureau confirmed that licensed banks and financial institutions review customers’ credit records before approving financing products, including car loans and personal loans. Such checks help lenders assess existing financial commitments, repayment history, and the applicant’s ability to manage additional debt.
Rent-to-own vehicle arrangements operate differently. Under these programs, customers make monthly payments for the use of a vehicle during an agreed contractual period, with ownership potentially transferring to the customer at the end of the term, subject to the contract’s conditions.
The bureau explained that rent-to-own arrangements are not classified as conventional loans and therefore do not inherently require the same credit inquiry associated with direct financing. However, participating providers may still request credit information, and many vehicle dealerships assess a customer’s creditworthiness before approving an agreement.
Customers were advised to examine all contractual terms carefully, including the calculation of monthly payments, any additional financial obligations, the conditions governing ownership transfer, and the regulatory status of the company offering the product.
The bureau also emphasized the value of reviewing personal credit reports to understand outstanding financial obligations, monitor repayment records, and identify inaccuracies. Maintaining a reliable payment history can help consumers make better financial decisions and avoid commitments beyond their repayment capacity.
The clarification highlights that rent-to-own arrangements may offer a different contractual route to vehicle ownership, but they do not guarantee approval without financial assessment. Consumers should understand the distinction between leasing and borrowing before entering any long-term vehicle agreement.
Source: Emarat Al Youm, citing Al Etihad Credit Bureau.
Thank you for being part of our community. Read our Comment Policy before posting.
Comments
Loading the conversation…