


RAK Ceramics reported higher third-quarter earnings as construction and project demand in the UAE helped offset weaker performance in several overseas markets.
RAK Ceramics Q3 Profit Rises 15.5% as UAE Demand Drives Sales
India Saudi Arabia United Arab Emirates
Font
Article text size
English fonts
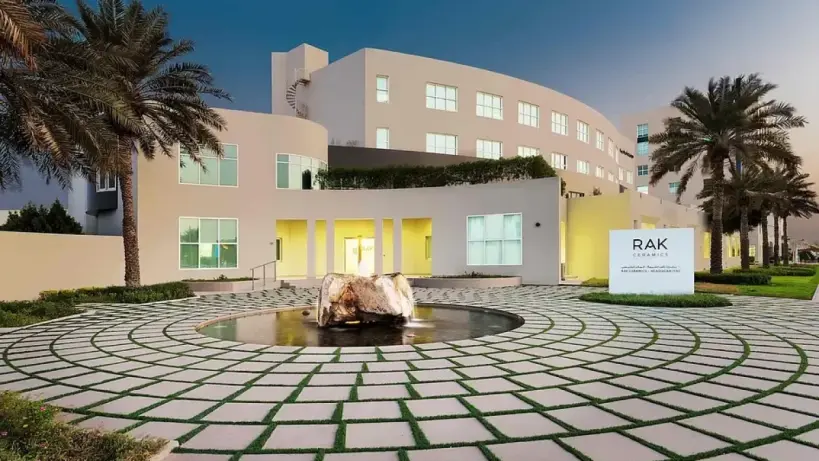
RAK Ceramics said strong UAE construction and project demand supported its third-quarter results.
The Abu Dhabi Securities Exchange-listed manufacturer said net profit after tax for the quarter ended September 30 rose 15.5% year on year to Dh78 million, from Dh67.5 million. Revenue increased 4.4% to Dh861.5 million.
Profit before tax grew 13.4% to Dh98.3 million, while EBITDA rose 4.7% to Dh175.7 million. Gross profit margin was largely unchanged at 40.3%, compared with 40.5% a year earlier, despite higher material and energy costs.
“We delivered a strong performance in Q3 2026, with revenue growth and double-digit profit growth despite continued geopolitical uncertainty, supply chain disruptions and elevated logistics costs,” chief executive Abdallah Massaad said.
UAE sales lead regional gains
Tiles, the group’s largest business, recorded revenue of Dh519.9 million, up 8.4%. The company attributed the increase to growth in the UAE, the Middle East and India, with project demand and constrained imports supporting sales in the UAE and wider Middle East.
UAE revenue from tiles and sanitaryware rose 32.5% to Dh313.8 million, driven by construction activity, project business and demand for slabs. RAK Ceramics said import disruption also helped it gain market share. Revenue in the Middle East excluding the UAE and Saudi Arabia increased 38% to Dh41.6 million, while India revenue climbed 12% to Dh92.8 million as its dealer network expanded.
Other markets declined. Revenue in Saudi Arabia fell 17.2% to Dh43 million, which the company linked mainly to delays in SABER approvals affecting deliveries. Europe revenue dropped 19.9% to Dh68.2 million amid higher logistics costs, competition and shipping delays. Bangladesh revenue declined 11.7% to Dh54.7 million because of gas shortages.
Sanitaryware revenue fell 7.3% to Dh114.8 million, as gains in GCC markets did not fully make up for weaker sales elsewhere.
Pricing and supply measures
Massaad said the company did not raise prices despite the disruption affecting trade and logistics. “We said we do not want to benefit from the situation and increase our prices, which we could have done,” he said.
He said RAK Ceramics used its manufacturing and distribution network across several countries, alternative logistics routes and inventory buffers to maintain supply. Technical teams also developed alternative formulations using locally sourced raw materials, although some imported materials remain necessary.
Massaad said the acquisition of Kludi had helped the group compete for hotel and major-project business by enabling it to offer tiles, slabs, sanitaryware, faucets and tableware together.
Nine-month performance and investment plans
For the first nine months to September 30, revenue was broadly flat, rising 0.7% to Dh2.45 billion. Net profit after tax increased 1% to Dh184.5 million, while profit before tax was broadly stable at Dh237 million. EBITDA slipped 0.8% to Dh460.5 million and gross margin remained at 40.3%.
Net debt stood at Dh1.59 billion at the end of September, up 4.7% from the end of June but 3.1% below its level a year earlier. The net debt-to-EBITDA ratio rose to 2.56 times from 2.48 times at June 30.
Capital expenditure during the nine-month period declined 24.6% to Dh162.5 million. Massaad said some spending plans had been delayed in response to market conditions, while the overall plan remained in place.
The group said its greenfield tiles plant in Yanbu, Saudi Arabia, remains scheduled for completion in the second quarter of 2027. It is also upgrading UAE factories, including its sanitaryware facility, with energy-efficient technology and measures intended to reduce carbon emissions.
| Metric | Q3 2026 | Year-on-year change |
|---|---|---|
| Revenue | Dh861.5 million | Up 4.4% |
| Net profit after tax | Dh78 million | Up 15.5% |
| Profit before tax | Dh98.3 million | Up 13.4% |
| EBITDA | Dh175.7 million | Up 4.7% |
| Gross profit margin | 40.3% | Down from 40.5% |
What do you think of this story?
Share your reaction, or help us correct a detail.
Thank you for being part of our community. Read our Comment Policy before posting.
Comments
Loading the conversation…